Sep 18, 2026
Last Updated: September 17, 2026
Qualifying for commercial vehicle leasing comes down to one question: can the lender see a stable business that can keep up monthly payments? Everything else, from your accounts to your trading history, feeds into that single judgement. At Minibus Leasing UK, we help schools, care homes and commercial fleets in Northampton and across the United Kingdom get finance approved, and the pattern is always the same. Lenders want proof of trading, proof of cash flow, and proof that the vehicle will earn its keep.
Below, we break down exactly what gets checked, what documents you need, and how to fix a weak application before you submit it.
Lenders treat trading history as the foundation of any decision. A business with two or three years of filed accounts is far easier to approve than a start-up with none.
Most funders look for:
Limited companies can usually point to filed accounts at Companies House. Sole traders and partnerships often need bank statements instead. A common mistake is applying with accounts that are over 18 months old. Lenders read that as a stalled business, even when trade is healthy.
Affordability checks look at what comes in and what goes out each month. A lender wants to see that lease payments fit comfortably alongside your existing commitments.
They will typically review:
For charities and care providers, restricted funding can complicate this. If your income arrives in grant tranches, say so upfront. Funders can work with lumpy cash flow when it is explained, but not when it is hidden.
The core business van leasing requirements are straightforward: a trading business, a UK bank account, and the paperwork to prove both. Eligibility does not demand perfect credit, but it does demand evidence.
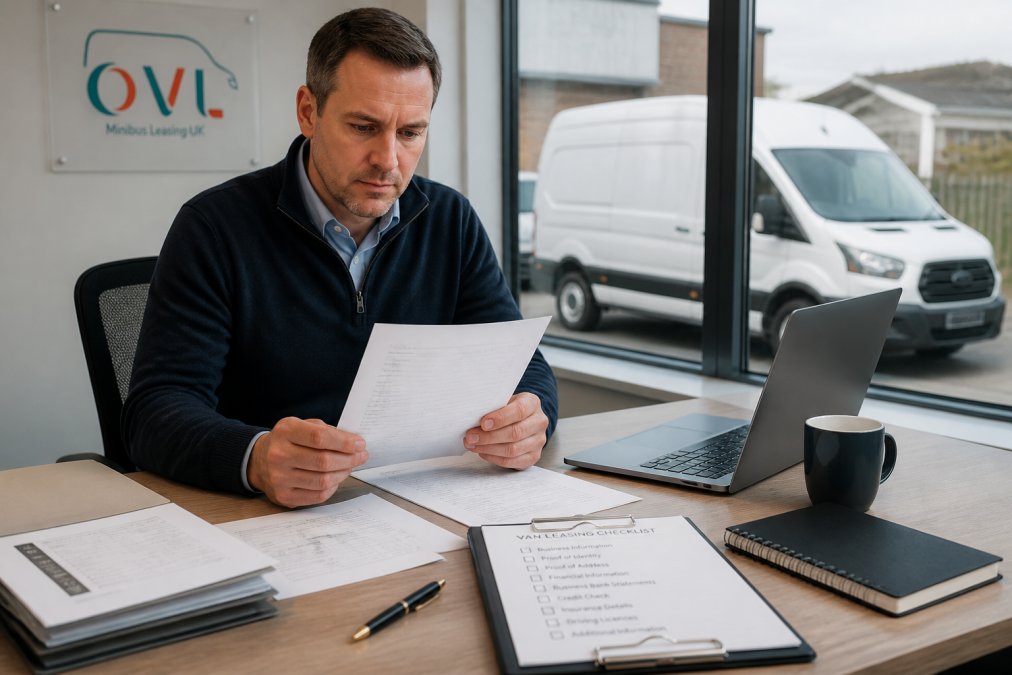
Use this checklist before you apply. Missing documents are the single most common cause of delay.
Sole traders often ask whether they need accounts at all. In practice, six months of clean bank statements plus a self-assessment return will usually satisfy a lender. Partnerships should provide the partnership agreement as well, since it confirms who can sign.
A commercial vehicle finance credit check differs from a personal one. Lenders search both the company and its directors, because a limited company's credit file is often thin on its own.
The check covers three areas:
One hard search usually appears on the director's file. Multiple applications in a short window can hurt your score, so avoid firing off several quotes at once. Give one funder the full picture first.
A declined application is not the end. Many funders specialise in different risk profiles, and a broker who understands the sector can match you to the right one.
The HMRC tax implications of business vehicle leasing depend on the vehicle type and how you use it. Getting this wrong costs money in either direction.
Get a Bespoke Quote or Speak to a Sector Specialist →
For vans used only for business, lease payments are generally allowable against profits, and you can usually reclaim VAT if the van is used exclusively for business. If there is significant private use, VAT recovery is restricted and you may face a benefit-in-kind charge.
For cars, the rules differ:
Always check current rates with HMRC guidance on vehicle benefits and expenses before you sign. Rates and thresholds change, and your accountant should confirm your position.
Operator licence requirements for commercial fleets apply when you run vehicles above certain weight limits or carry goods for hire or reward. Not every lease triggers one, but many do.
The main categories are:
For schools and community groups running minibuses on a voluntary basis, a Section 19 permit may apply instead of a full PSV licence. The rules around D1 licensing and permits catch people out regularly, and getting them wrong can invalidate your insurance.
If you are unsure which applies, ask before you order the vehicle. Retrofitting compliance after delivery is far more expensive than planning for it upfront.
Most declines trace back to a handful of fixable problems. None of them are permanent, and most can be resolved before you reapply.
| Problem | Why It Happens | How to Fix It |
|---|---|---|
| Thin credit file | New company, no filed accounts | Add a director guarantee or larger deposit |
| Missed payments | Old finance or cards paid late | Clear arrears, wait three months, reapply |
| Unclear cash flow | Lumpy or seasonal income | Provide 12 months of statements with context |
| Wrong vehicle class | Van quoted as car, or vice versa | Confirm tax and licence category first |
| Unregistered for VAT | Turnover below threshold | Not always a bar, but limits some funders |
A director guarantee is the most common fix for a young business. It shifts some risk back to you, but it gets the vehicle on the road.
The hardest part of qualifying for commercial vehicle leasing is not the paperwork. It is knowing which funder suits your sector, your size and your cash flow pattern. That is where most applications stall.
Minibus Leasing UK works with schools, care homes, charities and commercial operators across Northampton and the wider United Kingdom. Our team handles whole life cost analysis, so you can see the true cost of a lease against repairs and downtime. We know Section 19 permits and D1 licensing inside out, and every client gets a dedicated account manager who stays with you for the life of the agreement. We also run regular Minibus Leasing Special Offers and van leasing packages for growing fleets.
Get a bespoke quote or speak to a sector specialist, and we will match you to vehicles and terms that fit your budget and your compliance needs.
Most funders ask for proof of identity (driver's licence or passport), proof of address dated within three months, and business bank statements covering three to six months. Limited companies typically supply filed accounts or management accounts, plus a VAT registration certificate if registered. Sole traders and partnerships usually provide SA302 tax calculations or HMRC self-assessment records. Some lenders also request a signed lease application and a direct debit mandate. Having these ready before you apply speeds up the commercial vehicle finance credit check considerably.
There is no fixed minimum score. Lenders assess the whole picture: trading history, affordability, existing commitments and the strength of your business. A newer company with limited accounts may need a director's personal guarantee or a larger initial payment. A poor personal credit file does not automatically rule you out, but it may affect the terms offered. Speak to a specialist before applying so you know which lenders are most likely to accept your profile and avoid unnecessary searches on your file.
For limited companies, lease rentals on cars are generally allowable against corporation tax, though a disallowance applies to cars with a higher CO2 emissions figure. Vans and commercial vehicles are treated more favourably, with rentals normally fully deductible. VAT-registered businesses can usually reclaim 50% of the VAT on car lease rentals, or up to 100% on vans and commercial vehicles used only for business. Check current HMRC guidance or speak to your accountant for your specific circumstances.
It depends on the vehicle and what you carry. Vans and minibuses used for hire and reward, or for carrying goods in connection with a trade, may fall under operator licence requirements for commercial fleets. Minibuses used by schools, care homes or charities often need a Section 19 permit instead. Your leasing provider should confirm which category applies before contracts are signed. Getting this wrong risks fines and invalidates insurance, so verify the rules with the Traffic Commissioner or a compliance specialist first.

